CATL Reports Q3 Earnings
6 Min. Read Time
Key News
Asia investors celebrated SpaceX and SuperMicro’s strong post-US close financial results by buying AI-heavy Japan, Taiwan, and Korea. Vietnam had a strong day as well, while Mainland China, the Science and Technology (STAR) Board, Hong Kong, and India underperformed.
China's "National Team", i.e., investment firms associated with sovereign wealth, favorite ETFs had mixed volumes, though flow data is on a day lag; inflows have been strong in the last week. This indicates to me that the bottom may have been put in for the Mainland market (at least I hope so). The STAR Board was helped by semiconductor company Montage, which gained +8.97% in Hong Kong and +5.36% in Mainland China after announcing that Q3 net income will rise between 153% and 174% (RMB 1.2 billion to RMB 1.3 billion) year-over-year (YoY), significantly higher than analyst expectations of RMB 932 million. Montage, like many Chinese semiconductor companies, remains well off its 52-week highs on reports that big insurance companies plowed into the names post-Q2 just as Korea’s market collapsed.
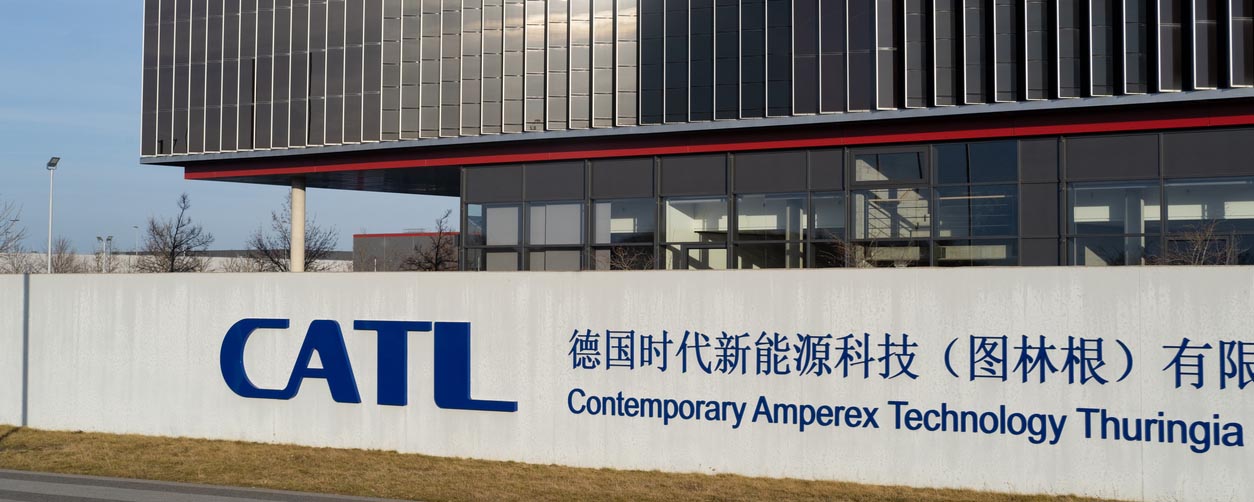
Reuters also reported SK Hynix and Samsung will upgrade their Chinese plants. The bigger issue for Hong Kong, Mainland China, and especially the Shenzhen Exchange was CATL’s earnings miss. CATL is often called "cattle", hence today's headline. The company announced the earnings miss after yesterday’s close, which sent its Hong Kong shares down -11.14% and its Mainland China-listed shares down -12.03%. The downdraft sent a shockwave through both markets’ consumer discretionary sectors, where auto, electric-vehicle, hybrid, and battery peers were hit har, as the battery giant’s margins were pressured by increased competition, domestic tax increases, and export tax increases. CATL’s Hong Kong shares hit a 52-week low after a -53% drop from the early-June high, amid increased chatter about these issues.Concerns about financial results for Pop Mart, which fell -4.84%, also weighed on the consumer discretionary sector.
Hong Kong-listed internet stocks were hit in the downdraft, as Alibaba fell by -1.14% on no news, similar ot JD.com, which fell by -1.63%. Tencent fell by -4.04% and was Hong Kong’s most heavily traded stock by 3X, hitting a 52-week low, and is now down -40% from its November 2025 high, as AI capex has been weighing on net income and earnings per share (EPS). Similar to Alibaba, Tencent appears to have reduced its buyback as a consequence of AI spending, though we’ll find out more on November 18th when they report.
Mainland investors sold Hong Kong stocks for the sixth straight day via Southbound Stock Connect. All in all, it was a dismal day in Hong Kong, except for healthcare, which appears to be becoming the best physical AI play. Telecommunication stocks were weak in both markets following China Mobile’s disappointing results. Semiconductor and electronic equipment stocks outperformed, though semiconductor equipment stocks were lower and electrical equipment stocks were mixed. The National Energy Administration reported September electricity consumption, which was up +1.2% YoY.
It was interesting that, in a Reuters interview, China-based automaker Chery said it was open to partnering with a US auto company. Maybe it will be announced at the Trump-Xi summit #3 or #4?
Australian data center company NextDC fell by -40% after cutting guidance due to issues garnering electricity consistently for one data center and having to stop new data center build-outs due to local opposition. This was regional news that was not highlighted in Western media.
KE Holdings bought back 393,852 Hong Kong-listed shares in last night's session, which the company announced after the close.
Last Night's Performance
Last Night's Exchange Rates, Prices, & Yields
- CNY per USD 6.67 versus 6.67 yesterday
- CNY per EUR 7.49 versus 7.48 yesterday
- Yield on 10-Year Government Bond 1.64% versus 1.64% yesterday
- Yield on 10-Year China Development Bank Bond 1.68% versus 1.66% yesterday
- Copper Price +0.49%
- Steel Price +0.36%