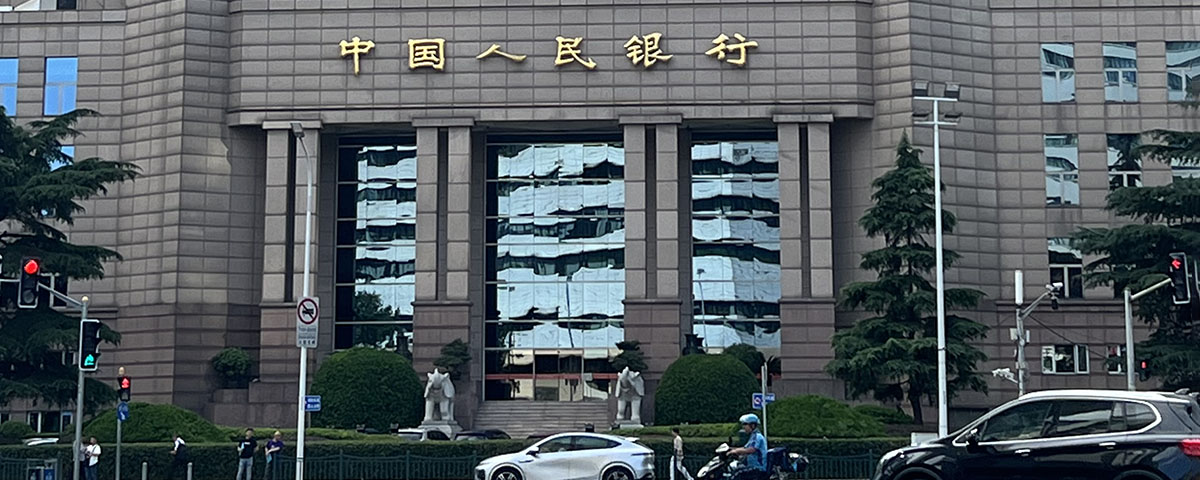
The PBOC Draws A Line In The Sand On Stock Market Support
7 Min. Read Time
Key News
Asian equities were mixed overnight, as Hong Kong, Mainland China, India, and Korea outperformed, while Singapore and Vietnam underperformed and the Philippines was closed for All Saints' Day.
Before market’s open, the People's Bank of China (PBOC), China's central bank, and the China Securities Regulatory Commission (CSRC), China’s SEC, and the State Financial Regulatory Commission announced they would meet with banks and financial institutions to discuss measures to support the stock market. This provided a risk-on tailwind. Later on in the session, the PBOC announced it will lend RMB 100 billion ($15 billion) via swaps to financial institutions to buy the stock market. It will also lower the loan rate to 1.00% from 1.25% for stock buybacks. Obviously, the swap loans can be reloaded indefinitely, as the vote of confidence comes at a critical time with indexes sitting on key support levels.
Both Mainland China and Hong Kong saw a pickup in volumes and breadth. The comeback was led by growth stocks, as the Science & Technology (STAR) Board gained +3.11%, the Hang Seng Tech Index gained +2.25%. Mega caps were mostly higher across the board, though banks underperformed in both markets. The move likely puts Hong Kong short sellers on edge, as light positioning in Hong Kong stocks had allowed them to press their bets.
The Mainland-listed domestic equity ETFs favored by China's "National Team", i.e. investment firms associated with sovereign wealth, had above-average volumes. Three ETFs reached a value traded that exceeded RMB 10 billion. At the same time, all but one of the eleven National Team ETFs that we track had above-average volumes. It is worth noting the three ETFs with the highest volumes track the CSI 300 Index, STAR Market 50 Index, and the ChiNext Index. That suggests that the National Team is spreading out their support with an emphasis on growth stocks.
There were several individual stock catalysts today:
- Xiaomi gained +6.12% after October auto sales exceeded 50,000, which is the highest monthly sales level year-to-date (YTD) following two months of declines. The company’s Sky Nomad N90 SUV, costing ~$40,000, is a sharp-looking SUV.
- October auto sales were also positive for BYD, which gained +3.22, and XPeng, which gained +4.33%.
- Battery giant CATL gained +6.08% in Hong Kong and +3.12% in Mainland China, likely driven by strong sales results from automakers.
- Alibaba gained +2.47% after securing Qwen as Apple’s Siri AI agent. Also, Qwen's office agent has achieved 30 million users in the first month after launch.
- Kuaishou gained +3.47% after reports that its Kling AI video unit had raised $2.98 billion, though we do not know the valuation following July’s round at a $15 billion valuation.
- YOFC gained +8.15% in Mainland China and +11.49% in Hong Kong in response to Q3 net profit growth of 1,741% year-over-year (YoY) and diluted earnings per share (EPS) growth of +1,595% YoY.
- Liquor giant Kweichow Moutai gained +3.38% after Q3 sales increased +3.1% YoY versus analyst expectations of 1%.
- Semiconductors rebounded in Mainland China, except for Cambricon, which fell -2.16%, and CXMT, which fell -0.19% after the latter’s disappointing Friday financial results. The AI supply chain was mixed in both markets.
- Brokerage stocks had a strong day as clear beneficiaries of the market policy support.
It was great to see a policy response to declining markets! A grind higher could be in the works. Hong Kong-listeed internet stocks' Q3 financial results, coming later on this month, could provide a further tailwind.
The “official” purchasing managers' indexes (PMIs), which were released by the National Bureau of Statistics (NBS), as October Manufacturing declined month-over-month (MoM) to 49.3 from September’s 50.1 versus expectations of 49.9 as orders and prices declined. The Non-manufacturing PMI also declined MoM to 49.7 from September’s 50.2 versus expectations of 50, also driven by a decline in orders and prices. The “private” Manufacturing PMI, survey conducted by S&P, was 52.0 versus September’s 52.1, which matched expectations of 52.0. Remember that there was a full week of work lost due to the week-long National Holiday.
Bloomberg Economics Chief Asia Economist Chang Shu noted how strong tech exports have been, writing “the AI wave is poised to propel China’s exports, offsetting headwinds from Fed hikes and yuan appreciation.”
NetEase bought bac 440,010 shares overnight. KE Holdings (US Ticker: BEKE) bought back 423,153 shares. Both companies announced the buybacks after the close.
Last Night's Performance
Last Night's Exchange Rates, Prices, & Yields
- CNY per USD 6.65 versus 6.65 on Friday
- CNY per EUR 7.45 versus 7.45 on Friday
- Yield on 10-Year Government Bond 1.63% versus 1.65% on Friday
- Yield on 10-Year China Development Bank Bond 1.68% versus 1.69% Friday
- Copper Price -0.56%
- Steel Price -0.66%