The Market Nobody Owns Has a Big Day
6 Min. Read Time
Key News
Asian equities experienced another unanticipated US election regime change following the Blue Wave, as the AI supply chain took another leg down in Japan, Taiwan, and Korea on data center build-out moratoriums. At the same time, investors rotated into widely under-owned anti-AI trades. Hong Kong, Australia, and India outperformed overnight.
A financial news TV anchor last night/Hong Kong morning noted the dramatic fall in Korea and Taiwan, stating investors appear to be rotating out of those markets, which “may benefit China, which nobody owns anymore”. It’s true! I’ll provide mutual fund positioning tomorrow to put some factual data behind the hyperbole.
Mainland media noted that a Trump-Xi-Putin meeting could occur following the Ministry of Foreign Affairs’ comments yesterday.
The Hang Seng +3.67% and Hang Seng Tech +5.55% both gapped higher as Hong Kong volumes increased +50% from yesterday to 140% of the 1-year average in the highest volume day since early July. Volumes by value traded were concentrated in the top stocks, led by Tencent +7.17%, Alibaba 8.45%, Xiaomi +8.83% and Meituan 6.78%.
Why do you think investors gravitated to those four stocks? Hint: Can you guess MSCI China’s top four holdings minus Chinese banks? Bingo! Minus three Chinese banks, you have MSCI’s top four holdings (Tencent #1, Alibaba #2, China Construction Bank #3, ICBC #4, Xiaomi #5)! Could be interesting to see how PDD, #7 in MSCI China’s top ten or #5 minus Chinese banks (Bank of China is #6), trades today, as it is only listed in the US. Remember MSCI’s definition of China is ~80% Hong Kong stocks, so you can’t have a “China rally” without Hong Kong’s top stocks outperforming.
Tencent was in the news following yesterday’s launch of Hunyuan Hy4, the latest version of its large language model (LLM), while Alibaba Cloud announced the integration of Moonshot AI’s Kimi K3.1 Pro LLM model.
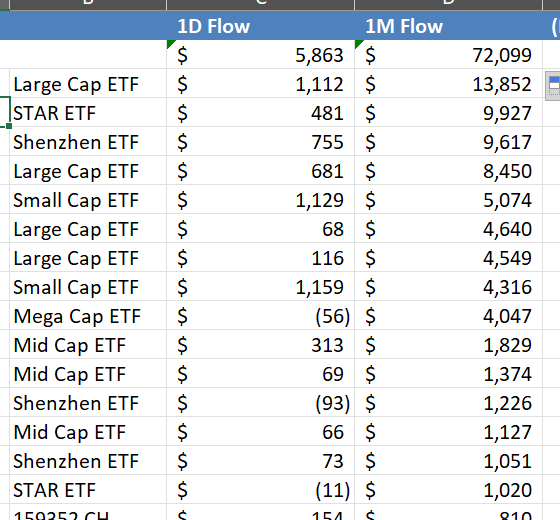
The National Team's favored China equity ETFs diverged, with large/mega-cap ETFs having below-average volumes, while Science & Technology (STAR) Board, Shenzhen, mid- and small-cap ETFs had above-average volumes. Only two ETFs exceeded the RMB 10B value traded level today, with one a STAR Board ETF and the other a Shenzhen-focused ETF.
Yesterday’s inflows totaled $5.8B across the 15 ETFs, with more than $1B in inflows over the last month. The largest inflows were led by mid-cap, small-cap, and large-cap ETFs. Inflows over the last month now total $72B! No PBOC updates on lending to facilitate today after yesterday’s announcement that RMB 200B in total had been lent to financial institutions for corporate buybacks.
Less oil/gas, coal, and semis were mixed; tech hardware, electronics, and communications were mixed/lower. Hong Kong had a very strong day, as advancers outpaced decliners handily.
BeiGene +7.34% hit a 52-week high as Q3 revenue +34% to $1.9B, adjusted net profit +77% to $539mm, and raised 2026 revenue to ~$7B. A Blue Wave beneficiary appears to be China clean tech, with CATL +4.67%, EV/hybrid and non-ferrous metals higher, as DC spending isn’t declining anytime soon.
Mainland investors took profits on their massive buy on Tuesday, selling $2.718B of ETFs and stocks.
Mainland China was up on very strong breadth, though indices were not nearly as much as Hong Kong, with big index weights like banks, coal, and oil/gas (PetroChina -7.93% and CNOOC -6.55%). AI supply chain was mixed, with semis outperforming as STAR Board +3.37%; tech hardware’s electronic equipment and communications were mixed. Somewhat quiet.
The State-owned Assets Supervision and Administration Commission met to discuss aligning SOE reforms with the 15th Five-Year Plan.
Hong Kong buybacks that took place today but announced after the close: KE (BEKE) Holdings 242,700 shares.
Last Night's Performance
Last Night's Exchange Rates, Prices, & Yields
- CNY per USD 6.66 versus 6.67 yesterday
- CNY per EUR 7.48 versus 7.50 yesterday
- Yield on 10-Year Government Bond 1.60% versus 1.61% yesterday
- Yield on 10-Year China Development Bank Bond 1.65% versus 1.66% yesterday
- Copper Price +0.08%
- Steel Price +0.1.03%