The “National Team” Buys ETFs Early & Often, Week in Review
7 Min. Read Time
Week in Review
- Asian equities were mostly lower for the week, as Indonesia and Vietnam outperformed, managing gains, while Hong Kong and Japan underperformed.
- China's GDP growth in Q3, reported Monday, was +4.5% versus an expected +4.4% year-over-year (YoY).
- China's "National Team", i.e. investment firms associated with China's sovereign wealth, appear to have been active this week, stepping in to support the market through significant purchases domestic equity ETFs amid a global sell-off in AI supply chain stocks.
- Q3 earnings releases this week were mixed a Montage Semiconductor beat expectations, while battery maker CATL missed.
Friday's Key News
Asian equities bounced back following yesterday’s wipeout, led by China’s Science & Technology (STAR) Board and Hong Kong’s Hang Seng Tech Index, while Thailand was closed for the National Holiday and Taiwan got a four-day weekend after closing today for a typhoon in advance of Monday’s holiday.
Was today an oversold technical bounce or the bottom for Hong Kong and Mainland China? Time will tell, though, as we noted crowded positioning is a factor. However, positioning in China, vis-a-vis the AI supply chain, did not reach the extremes of MSCI Taiwan, which is 50% TSMC, and MSCI Korea, which is 50% SK Hynix and Samsung. This could lead to broadening out to non-AI market segments. Throw in Thursday’s offshore trust tax bill coming due, exceedingly light positioning in Hong Kong-listed stocks, and Hong Kong indexes slicing through big round numbers, which triggers stop loss and immediate selling in underlying index futures and stocks, against the backdrop of no buyers, and you get yesterday's steep drawdown.
Mainland China opened lower, hitting intraday lows. The Shanghai Composite opened down -2.29%, the Shenzhen Component opened down -3.38%, and the STAR Board opened down -3.72%. Then, in the late morning, the "National Team" started buying favored ETFs. That contrasts with their actions on Thursday, when they sat on their hands until the last hour of trading, which was too little, too late. The National Team’s favored ETFs had high volumes, while inflow data shows two ETFs had inflows of $1.56 billion and $1.42 billion.
Hong Kong opened slightly lower but grinded higher despite Mainland investors selling Hong Kong-listed stocks and ETFs via Southbound Stock Connect. In both markets, defensive plays, including banks, were lower, while yesterday’s AI supply chain losers, i.e. semiconductors, semiconductor equipment, electrical equipment, and electronic components, were today’s winners. Autos were also winners overnight, as battery giant CATL bounced back on large buybacks. Non-ferrous metals were also higher overnight.
After the close, the China Passenger Car Association announced September auto exports increased +55% year-over-year (YoY) to 1.2 million cars. That brings the year-to-date (YTD) export growth to +52% YoY and 8.6 million units.
Hong Kong’s most heavily traded stocks by value were Tencent, which gained +0.94% on strong buying via Southbound Stock Connect, and Alibaba, which gained +0.46% despite net selling from Mainland investors via Southbound Stock Connect. It was interesting to see consumer plays continue to rebound, including home appliances. The recent used home mortgage reduction and RMB 550 billion worth of local government bond sales appear to be counting as small, incremental stimulus measures.
Deepseek’s $15 billion raise and offshore business approvals lifted Z.AI, which gained +8.29%, and Minimax, which gained +16.74%. Healthcare did well, despite headlines suggesting the US government could curb private-equity biotech investments. It is interesting timing considering the number of global pharmaceutical deals with Chinese biotech firms and the recent Trump-Xi meeting.
Although it was likely not a factor in last night's market action, but the State Council did release a document called “Opinions on Adapting to Artificial Intelligence Technology Development and Helping Build an Employment-Friendly Development Model". The document only reinforces the potential government policy tailwind. The Standing Committee of the 14th National People’s Congress will be held from November 2nd to 6th and could provide further policy guidance.
Citigroup was approved to operate independently in China’s onshore financial markets. The global bank became the 7th foreign securities firm with such an approval, another outcome example of Trump Xi summit #2. Summit #3 will be at APEC in Shenzhen next month and #4 will be on the sidelines of the G20 in Miami.
It is amazing to see resilience in China’s currency, the renminbi (RMB or CNY) versus the US dollar. Last night, the currency hit a 52-week high of 6.67 per US dollar.
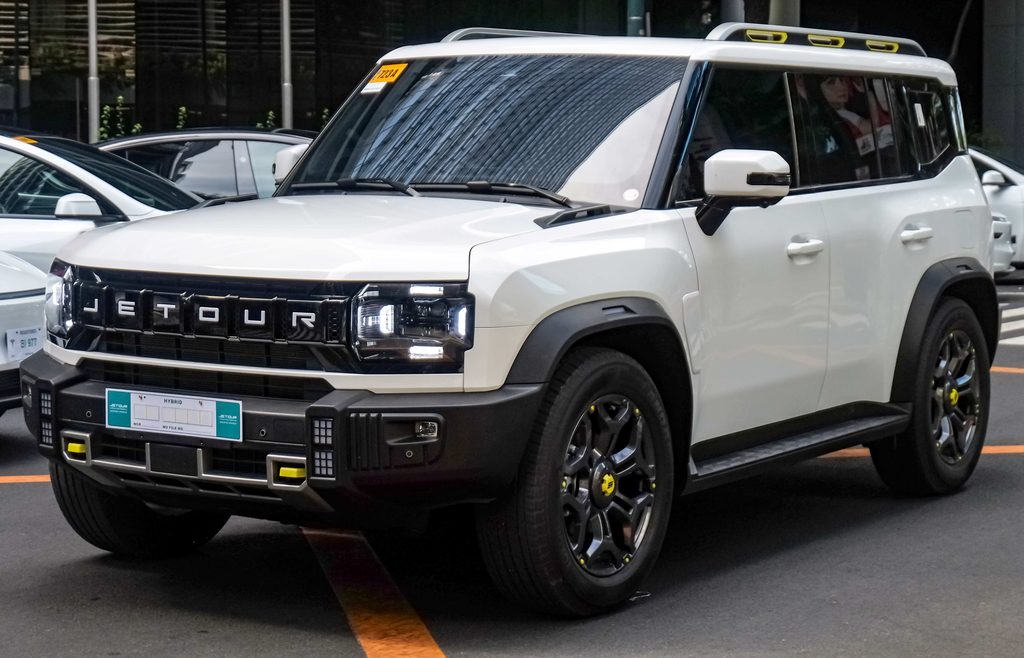
While in Latin America this week, I saw several Jetour cars which are a brand of the China-based automaker Chery. I did not have the chance to ride in one, but they looked great. I was shocked at the sticker prices. The Jetour T2 plug-in hybrid SUV (pictured below) costs $40,990, while the Jetour X50, a smaller SUV, costs $13,990. There are rumors that Chery might build a factory in Canada, which is interesting.
I stumbled across this Robert Greene quote “Be consoled that nothing will last, including the depression or disappointments we feel in the present.” Hopefully, this applies to investors in Hong Kong.
Last Night's Performance
Last Night's Exchange Rates, Prices, & Yields
- CNY per USD 6.67 versus 6.67 yesterday
- CNY per EUR 7.47 versus 7.48 yesterday
- Yield on 10-Year Government Bond 1.64% versus 1.64% yesterday
- Yield on 10-Year China Development Bank Bond 1.68% versus 1.68% yesterday
- Copper Price -0.71%
- Steel Price -0.69%